Your Local Mortgage Lender
Located in Southlake, Texas
Personalized Mortgage Experience
David White offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Southlake, Texas.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
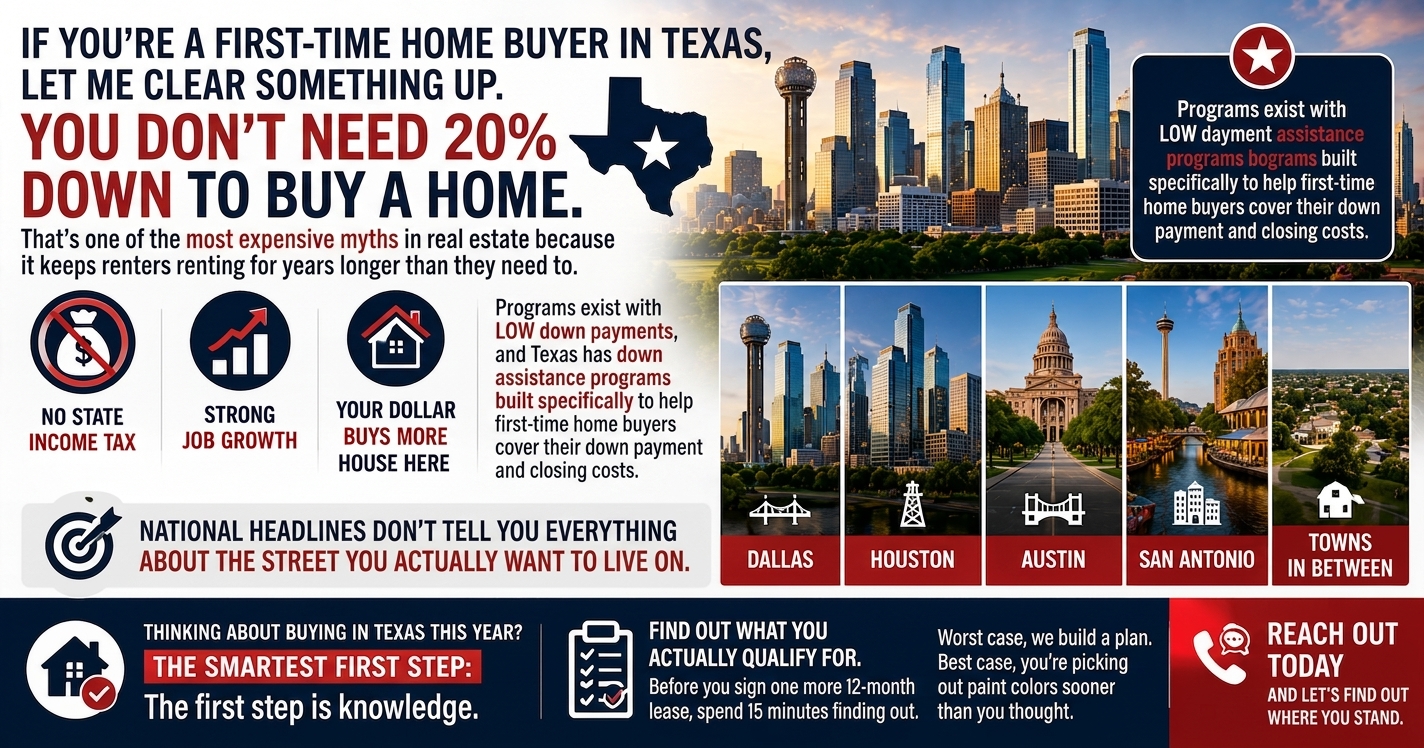
Texas First Time Buyers Do Not Need 20 Percent Down and Here Is What You Actually Need to Know
The Myth That Is Keeping Texas Renters From Buying Years Sooner Than They Have To
If you are a first-time homebuyer in Texas there is a persistent and expensive misconception worth clearing up before you sign another twelve-month lease. You do not need twenty percent down to buy a home. That belief is one of the most costly myths in real estate because it keeps renters renting far longer than their actual financial situation requires.
What the Down Payment Options Actually Look Like
Low down payment loan programs exist and are widely available to qualifying buyers. FHA loans require 3.5 percent down. Some conventional loan programs require as little as 3 percent. VA loans for eligible veterans require zero down. USDA loans for qualifying rural and suburban areas also offer zero down payment options.
Beyond the loan programs themselves Texas has down payment assistance programs built specifically to help first-time buyers cover their down payment and closing costs. These programs exist at the state level and through various local and municipal initiatives and most first-time buyers have never checked whether they qualify for any of them.
The number you have been saving toward may be significantly larger than what any of these programs actually require. The gap between what buyers assume they need and what the programs actually ask for is often the entire reason a buyer is still renting.
How Close You Might Actually Be
As David White explains while you are working toward the large number you have set as your savings target you might already be closer to homeownership than you realize. The qualification conversation is the only way to find out where you actually stand rather than estimating based on assumptions that may not reflect what is currently available.
That conversation takes about fifteen minutes. The outcome is either a clear picture of what you qualify for right now or a specific plan that shows you exactly what needs to happen and how long it will actually take to get there. Either result is more useful than continuing to save toward a target that may be larger than necessary.
The Challenge Worth Taking
Before you sign one more twelve-month lease spend fifteen minutes finding out what you actually qualify for. Worst case you walk away with a real plan. Best case you are picking out paint colors sooner than you thought was possible.
Message David White today and find out where you stand.
Sources
TexasAssociationofRealtors.com
HUD.gov
ConsumerFinancialProtectionBureau.gov
TexasDepartmentofHousing.gov
MortgageNewsDaily.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Important Pages
Terms of Service
Privacy Policy
Accessibility Assistance
Quick Links
Programs
Blogs
About Us
